
- Rising construction costs and project disruptions pose scheduling and utilization risks for cement and asphalt haulers.
- Contractor surveys show pressure, but highway spending, backlog, and available cement-shipment data present a mixed demand picture.
- The practical test is whether customers turn planned work into confirmed material orders and delivery dates.
Construction cost pressure is creating a harder planning environment for bulk carriers supplying concrete plants and paving operations. Higher project budgets can push work back, reduce its scope or keep it from starting, putting expected cement, supplementary cementitious material and liquid-asphalt movements at risk before a truck is dispatched.
The Associated General Contractors of America reported September 10 that the producer price index for inputs to new nonresidential construction rose 8.9% from August 2025 to August 2026. Its analysis of federal price data describes a cost squeeze alongside contractor reports of interrupted projects.
For tank and dry-bulk fleets, the immediate concern is how reliably expected work becomes a load. The available evidence supports that concern, while stopping short of establishing a nationwide decline in bulk-hauling demand. Some construction markets remain comparatively resilient, and the newest indicators do not all point in the same direction.
Project Disruptions Put Expected Loads at Risk
AGC’s 2026 workforce survey with NCCER asked contractors whether projects were canceled, postponed, or scaled back in the previous six months. Among the 781 respondents who answered that question, 55% reported such disruptions. 34% cited rising costs, and 27% cited unavailable or expensive financing.
Respondents could select multiple reasons. Those percentages therefore cannot be added together, and the 55% figure describes the share of responding firms affected. It does not mean 55% of projects were canceled or that an equivalent share of construction freight disappeared.
The distinction matters for dispatch. A postponed project may retain its original material requirements but shift them into another month. A smaller project may reduce total tonnage. A cancellation may remove the expected work altogether. Each creates a different problem for a carrier that has reserved drivers, trailers, or loading appointments.
Consider a cement hauler expecting repeat deliveries to a ready-mix plant for a scheduled foundation pour. If the pour moves, the plant may revise its replenishment orders. The carrier’s exposure depends on the plant’s inventory and other customers: it might lose a day’s work, move the loads to later in the week, or see little immediate change.
That is an operating scenario, not a measured result from the contractor survey. It illustrates why a project announcement or a customer’s broad sales forecast is less useful for fleet planning than a confirmed order tied to a receiving date.
Cement and Asphalt Face Different Price Signals
The broad construction index also masks substantial differences among materials. AGC’s August price tables, drawn from Bureau of Labor Statistics data, show cement prices below their year-earlier level, while ready-mixed concrete and refinery asphalt prices were higher.
| Material | Year-over-year change | What the comparison separates |
|---|---|---|
| Cement | −1.2% | The powder supplied to concrete production. |
| Ready-mixed concrete | +2.3% | A downstream product with a different cost structure. |
| Asphalt at refineries | +16.4% | A petroleum-product price, separate from trucking rates. |
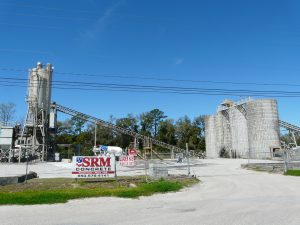
Silos, conveyors and a mixer truck at SRM Concrete’s Mill Street facility in Tallahassee, Florida. (Photo: The Bushranger/Wikimedia Commons; CC BY-SA 4.0)
Refinery asphalt prices also fell 9.6% between July and August. The monthly decline and annual increase can coexist: they compare different starting points. Neither measure alone establishes what a particular terminal customer will pay or how many loads a paving contractor will order.
For cement haulers, lower cement prices offer no guarantee that customers’ entire projects become affordable. Labor, equipment, financing, and other materials remain part of the owner’s decision. For asphalt haulers, a change in binder cost may alter project economics without immediately changing the delivery schedule.
The freight question is how much material to order and when it must move. A producer-price index helps explain the customer’s cost environment; confirmed purchases and delivery instructions establish the carrier’s available work.
Highway Spending and Backlog Complicate the Outlook
The Census Bureau’s July construction-spending report, released September 1, estimated total spending 3.8% below July 2025. Public highway and street spending, however, was 4.5% higher, at a seasonally adjusted annual rate of approximately $150.3 billion.
These are dollar measures, unadjusted for price changes, and the annual rate is not the amount spent during July. They cannot be converted directly into cement tons or asphalt tanker loads. They do show why a fleet supplying road work may face a different market from one concentrated on private building projects.
Contractor backlog provides another counterweight. Associated Builders and Contractors reported September 15 that its Construction Backlog Indicator rebounded to 8.5 months in August, up half a month from July and unchanged from a year earlier. That indicates substantial work remained in the surveyed contractors’ pipeline.
Backlog still requires careful interpretation. It is not a delivery calendar, and the national measure cannot reveal whether a particular concrete plant will need extra cement next week. Work can remain on the books while its material-intensive stages shift.
Physical shipment data serve a different purpose. The U.S. Geological Survey’s April 2026 cement report, published in September, estimated 9.27 million metric tons of portland and blended cement shipments, including imports, in the United States and Puerto Rico, up 2.0% from April 2025. January-April shipments were up 5.1%.

A paving crew lays asphalt as a dump truck feeds material into the paver in Redmond, Oregon. (Photo: Tom Shamberger/Pexels)
Those figures counter an assumption of uninterrupted cement weakness throughout 2026. Their reporting period also limits their usefulness: April shipments cannot settle the late-summer demand question. They cover the cement market across transportation modes, rather than a dedicated measure of pneumatic-trailer activity.
Together, the indicators describe an uneven market. Costs are pressuring projects, yet some spending and work pipelines remain supportive. Geography, customer mix, and construction stage determine how much of either condition reaches a bulk fleet.
When a Project Delay Becomes a Fleet Cost
For a carrier, the first financial effect of a postponement may appear in equipment utilization before it appears in annual tonnage. Work moved into a later week can leave capacity unproductive today and create competing delivery demands when several projects restart together.
A carrier whose surcharge reimburses fuel-price changes may still face lost truck-days when work is rescheduled. Fuel recovery and equipment utilization answer separate financial questions. Tank Transport’s examination of diesel surcharges and cash flow addresses benchmark timing and recovery on the loads that actually move.
A project can remain in the backlog while its expected loads move off this week’s dispatch board.That makes the quality of the customer’s schedule important. A tentative start date, an awarded contract, and a confirmed material release represent different levels of certainty. Tracking them separately helps dispatch see which loads are firm and which still depend on financing, approvals, or site readiness.
For cement and supplementary cementitious material deliveries, useful questions concern the receiving plant’s production plan, available storage, and expected replenishment cycle. For liquid asphalt, they should focus on the paving program and the terminal or plant’s confirmed requirements. These conversations can surface a schedule change before a truck begins an unnecessary repositioning move.
Relevant operating measures include completed loads per available truck-day, empty miles, waiting time, and the difference between forecast and actual orders. Tank Transport’s analysis of bulk-carrier operating economics explains why loaded-mile revenue alone can miss the cost of capacity commitments and unproductive time.
A shifted delivery also deserves to be distinguished from an inefficient transfer. The first depends on customer demand and project timing; the second may be addressed within the loading and receiving process. Our examination of dry-bulk loading and unloading covers those transfer constraints. Faster unloading can improve an existing movement, but it cannot replace a postponed material order.
Before committing more equipment to a projected increase, a fleet can compare the customer’s expected tons with confirmed releases and actual recent shipments. Repeated shortfalls warrant a closer discussion about timing and capacity. A strong order book backed by consistent releases supports a different decision.
Construction cost pressure therefore calls for closer attention to how projects become freight. The next spending and shipment reports will help establish direction, but the near-term operating signal is whether customers keep, move, or reduce the loads already expected.
Construction Freight Outlook: Key Developments
- Cost pressure: Nonresidential construction inputs rose 8.9% year over year in August, while individual material prices diverged.
- Project risk: AGC’s survey documents disrupted work; its percentages measure affected respondents, not lost freight volume.
- Mixed demand: Public highway spending and the August backlog rebound temper a broadly negative market read.
- Dispatch priority: Watch confirmed material releases, revised delivery dates, and utilization to identify where project delays are reaching the fleet.