
- Milk production is growing unevenly across major dairy states, changing the supply picture for regional hauling networks.
- USDA reports continuing distribution constraints even as more milk becomes available.
- Processor commitments, receiving schedules, and tanker turnaround determine how additional supply translates into hauling work.

A milk tanker at Wanner’s Farm in Narvon, Pennsylvania, illustrates the farm-collection end of the dairy supply chain. File photo, October 2014. (Photo: Beyond My Ken/Wikimedia Commons, CC BY-SA 4.0)
Milk production growth is adding supply to the U.S. dairy system, but regional distribution constraints continue to complicate its movement. USDA’s October 22 Milk Production report puts September output in the 24 major states at 18.7 billion pounds, up 2.7% from a year earlier. The all-state estimate rose 2.6% to 19.4 billion pounds.
For dairy haulers, cooperatives and processors, the consequential question is where that milk can go. A statewide production gain does not identify the farms offering additional pickups, the plants accepting deliveries or the carriers positioned to handle them.
The latest figures bring a new distribution angle to the Western milk-hauling cost pressures Tank Transport covered earlier this month. Production, access to uncommitted milk and compensation for moving it are separate measures. Growth in the first can coexist with difficulty in the other two.
Milk production growth varies sharply by state.
The September figures show substantial differences among major producing areas. These selected states illustrate the range; they are not a complete regional balance sheet.
| State | Million pounds | Change from September 2025 |
|---|---|---|
| California | 3,290 | Less than +0.05% |
| Wisconsin | 2,782 | +3.3% |
| Idaho | 1,595 | +3.5% |
| Texas | 1,562 | +4.1% |
| New York | 1,417 | +4.2% |
| Kansas | 492 | +14.7% |
| Arizona | 350 | −4.9% |
Percentage growth and additional pounds tell different stories. Wisconsin added 88 million pounds from a larger base, compared with Kansas’s 63 million. Neither comparison establishes how much additional business became available to an independent carrier.
For a fleet evaluating expansion, a production map is a starting point for conversations with handlers; the next questions concern farm locations, existing transport agreements, and receiving destinations. More output from farms already on a route might improve loading efficiency; growth requiring a separate collection area could create a substantially different service commitment.
Those are possible operating outcomes, not findings from the production survey. Converting statewide pounds directly into an estimated number of available tanker loads would conceal the missing route and contract information.
More supply does not mean more uncommitted milk.
USDA’s Dairy Market News report for October 19–23 describes limited Central-region spot milk for cheesemakers as Class I and IV activity increases. Its butter commentary identifies freight and distribution difficulties affecting both milk and cream. Eastern cream supplies were heavy, while Western availability varied, with spot milk available in the mountain states.
These weekly observations describe trading conditions after the September production period. They cannot establish that September’s additional milk caused October’s constraints. Read together, however, the reports show why farm output and a buyer’s ability to obtain an extra delivery need separate evaluation.
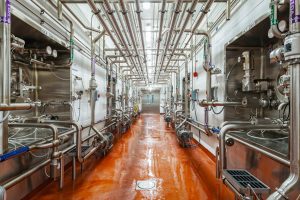
Stainless-steel piping and tanks inside a Ninth Avenue Foods dairy-processing facility illustrate the processing infrastructure behind farm-to-plant milk movements. (Photo: Ninth Avenue Foods)
The USDA milk-use classifications help explain the competition. Class I covers beverage milk; Class II includes products such as yogurt and frozen desserts; Class III includes cheese; and Class IV includes butter and dried milk products. These categories describe utilization, rather than a common pool of freight available for reassignment.
A processor can need additional milk while another plant has enough under existing contracts. A carrier serving the second plant does not automatically gain access to the first plant’s business. The supplier, destination, and transportation arrangements must align before a market shortage becomes an executable load.
More milk becomes an additional load only when supply, a receiving plant, and a tanker schedule align.Milk and cream also require separate dispatch attention. Central manufacturers were taking near-maximum contracted cream volumes while spot availability varied locally. That describes their contracted intake, not a measured ceiling on every plant’s receiving capacity. A report of abundant cream elsewhere does not establish the availability of an equivalent volume of whole milk, or an open receiving appointment for either product.
Longer tanker cycles can absorb apparent capacity gains.
Processing geography matters independently of production growth. University of Wisconsin–Madison Extension’s milk-hauling reference explains that fluid plants tend to locate near customers, while cheese plants tend to locate near milk supplies. It cites modeled average hauls of 101 miles to fluid plants and 20 miles to cheese plants. Those are model results, not observed averages for today’s routes.
The implication is that a destination change can alter transportation demand even when the pounds collected remain unchanged. Tank Transport’s August coverage of Vermont milk rerouting after the St. Albans shutdown provides another example of how a processing change can reshape the hauling network. It is background context, not evidence of the cause of this month’s Central-region constraints.
Consider an illustrative capacity calculation. If a complete tanker cycle lengthens from 10 hours to 12 hours, the same available equipment-hours support about 17% fewer cycles, assuming unchanged payloads and no additional equipment or operating hours. That arithmetic is not a measured industry result. It shows why the time required to complete a movement can outweigh a modest change in milk volume.
For dispatch, the relevant interval includes collection, travel, unloading, and the return or repositioning needed for the next assignment. A distant plant with dependable receiving may produce a different result from a closer plant with an uncertain unloading window. Actual trip records are needed to identify which arrangement uses capacity more effectively.

Milk-hauling trucks at the Centerport Milk Hauling Cooperative in Pennsylvania, June 2015. (Photo: Shuvaev/Wikimedia Commons; CC BY-SA 4.0)
Receiving eligibility also needs confirmation. FDA’s Interstate Milk Shippers List covers listed milk supplies, plants, receiving stations, and transfer stations within the Grade A sanitation program. A listing can inform that check; it does not establish that a facility has space, staff, or a commercial agreement to accept a particular tanker.
What would demonstrate a better hauling market?
The current reports establish a need to examine regional distribution. They do not quantify a national shortage of milk tankers or identify how much of the reported difficulty comes from driver availability, equipment, receiving capacity, or commercial arrangements. Assigning the entire problem to any one factor would go beyond the evidence.
For carriers, the distinction matters when negotiating additional service. A request for occasional overflow deliveries is different from a recurring route with committed volume. Both can add revenue, but their requirements for equipment availability, driver scheduling and repositioning may differ substantially.
A useful review therefore starts with the movement being purchased: origin, accepted destination, expected payload, timing and responsibility for changes. If a receiving plant redirects a tanker after collection, the agreement should make clear how the additional distance and elapsed time affect payment. A quoted rate has limited meaning without that service definition.
Milk-price signals require similar care. The Central-region spot range in the October report was the Class III price to $4 per hundredweight above it. That premium is a commodity-market measure; it does not reveal the carrier’s compensation or margin. Extension also notes that hauling charges are negotiated and distinguishes producer milk-check deductions from measured transportation costs. Neither a higher milk price nor a changed deduction proves that a hauling business earns more.
The next useful evidence is specific: repeated requests for loads on identifiable routes, confirmed receiving arrangements, actual turnaround times, and revenue that covers the completed service. Fleet records can test those conditions against the broader USDA commentary. Tank Transport’s Tank & Bulk Markets brings dairy indicators and regional diesel information together for continued monitoring.
Dairy Distribution: Key Developments
- Production geography matters: State totals help identify where to investigate new hauling demand, but do not establish available contracts.
- Availability has several meanings: Farm output, uncommitted product, and accepted deliveries need separate checks.
- Turnaround determines usable capacity: Additional distance or waiting can reduce the work existing equipment completes.
- Carrier results need direct evidence: Completed-route revenue and costs are more informative than milk-price movements alone.
The practical test for the coming weeks is whether suppliers, processors and carriers can turn additional production into reliable, adequately compensated movements. That will become visible in delivery schedules and completed tanker cycles before it can be inferred from another national production headline.
Featured photo: Milk tanker at Darigold’s dairy in Issaquah, Washington, June 2009. File photo; cropped for the header. (Photo: Joe Mabel/Wikimedia Commons; CC BY-SA 3.0)